8.22 | Jubo Weekly: Two glass lines restart N.China; inventories dip. Al futures‑spot fluctuate, stocks drop.

Float Glass|Production Line Dynamics This Week
8.18
-
Tianjin Yaopi Line 2 (designed capacity: 600 t/d) resumed operation after ignition.
-
Shanxi Qingchun Line 2 (designed capacity: 600 t/d) resumed operation after ignition.
Float Glass|Price Market This Wee
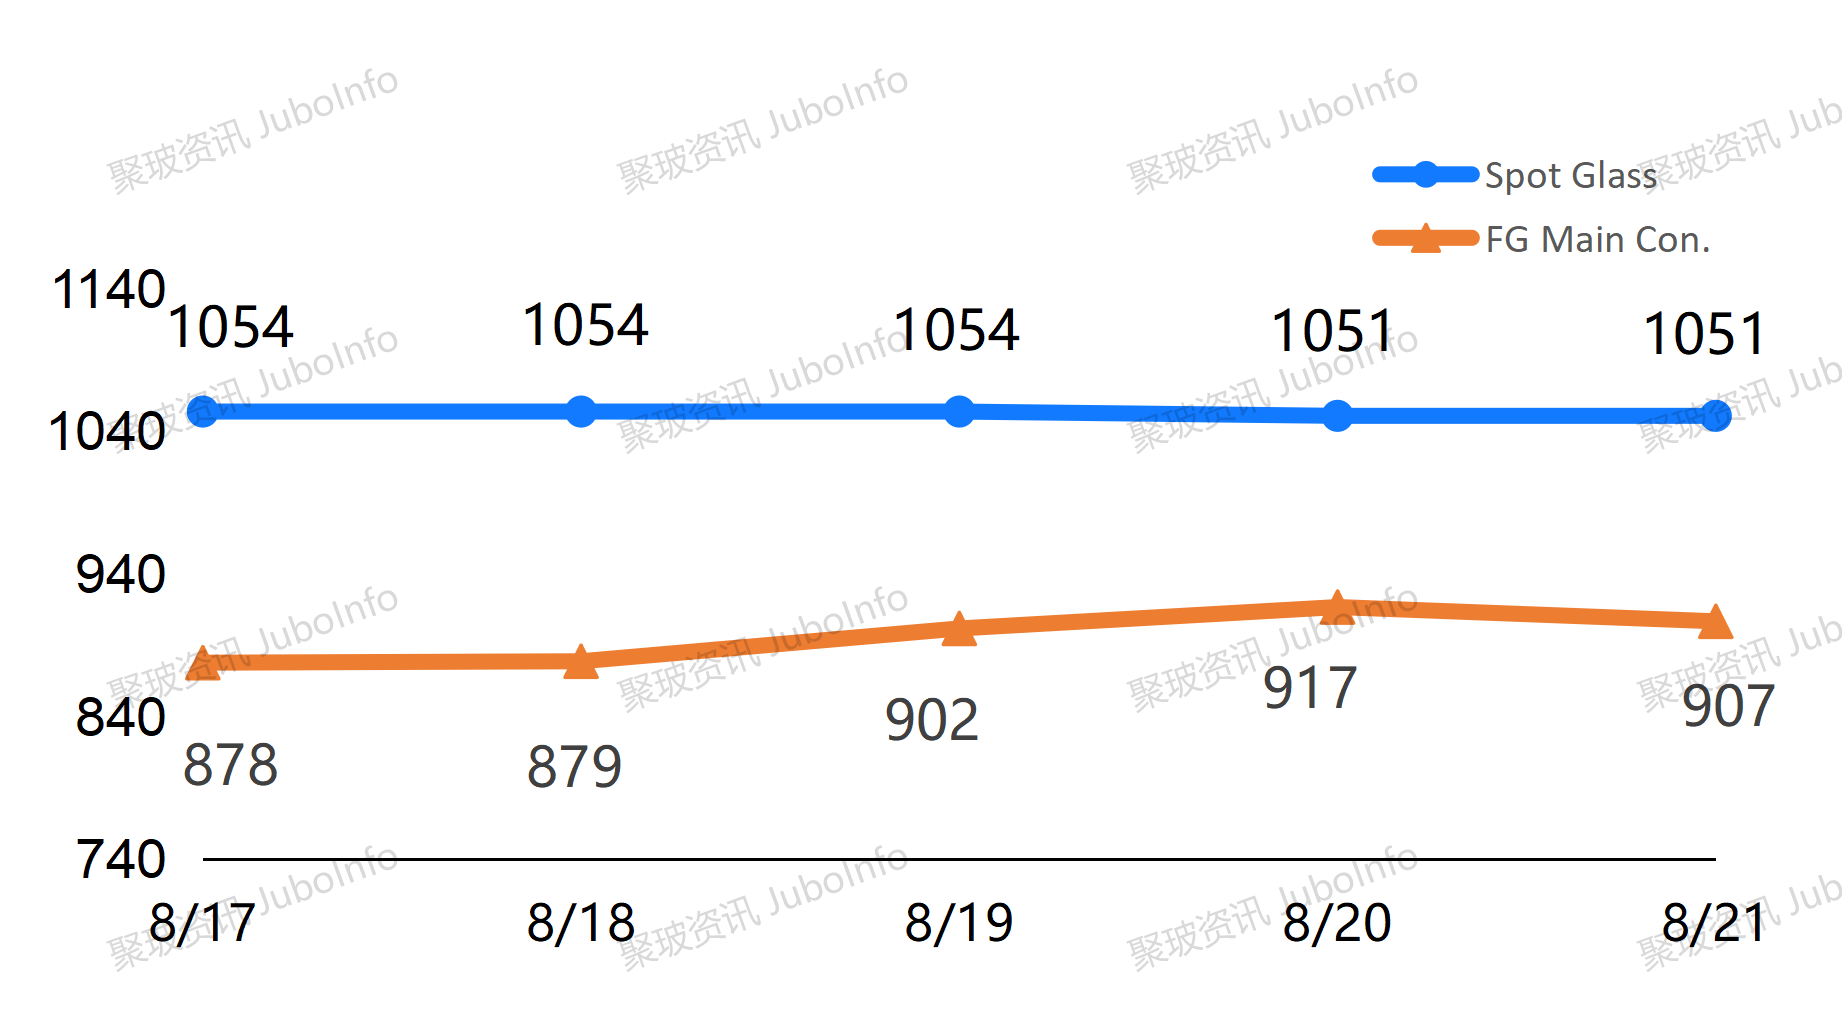
National Average Price of Float Glass
-
Roll‑over took place for the main glass futures contract (switch from FG2609 to FG2701). Spot prices weakened amid stability. Downstream demand remained sluggish; producer quotations rose and fell mixed, with overall transaction centres moving lower. On the supply side, two lines restarted, lifting the comprehensive operating rate. Enterprises mainly purchased on dips. Producers aimed to reduce inventories with flexible sales. Regional production‑sales performance varied; industry destocking proceeded slowly. Short‑term spot market is expected to fluctuate steadily.
-
Glass inventories edged down this week. Total inventory of sampled national float‑glass producers stood at 74.414 million weight‑cases, down 56 000 weight‑cases week‑on‑week (‑0.07%), up 17.41% year‑on‑year.
Average Prices of Float Glass by Region

-
North China:Downstream demand remains driven by essential procurement needs; there are regional disparities in production, sales, and inventory levels; some suppliers have lowered their quotations; and manufacturers are experiencing mixed inventory trends.
-
East China:Replenishment demand in the mid-to-downstream segments is limited, while there is a strong market sentiment toward reducing inventory levels; in certain regions, manufacturers are primarily engaging in flexible shipping activities.
-
Central China:Some manufacturers have lowered their quotations to stimulate shipments, leading to a slight downward trend in market prices; overall, production and sales remain above equilibrium.
-
South China:Driven by the impact of low-priced supply from overseas markets, manufacturers across various regions are offering preferential pricing for shipments; downstream demand remains primarily driven by essential purchasing needs, resulting in a slight overall inventory buildup.
-
Northeast China:Phased inventory buildup on the demand side has driven strong regional shipments.
-
Southwest China:Rising quotations from manufacturers in the Yunnan–Guizhou region have, to some extent, boosted market sentiment, while some manufacturers have begun reducing their inventory levels.
-
Northwest China:There are discrepancies in inter-regional shipment levels; the market is operating in a weak yet stable manner; overall inventory levels have seen a slight increase.
PV Glass|Price Market This Week
Average Prices of 3.2mm Photovoltaic Glass by Region

Average Prices of 2.0mm Photovoltaic Glass by Region

-
Domestic PV‑glass spot market stayed weak. Producers mostly kept prices stable; trading remained muted. No production‑line changes on the supply side. Downstream maintained cautious rigid‑demand buying. Shipments slowed and some inventories rose marginally. PV‑glass prices are projected to stay stable in the near term.
Soda Ash|Unit Dynamics This Week
Soda Ash|Price Market This Week
Light Soda Ash Prices by Regions

Heavy Soda Ash Prices by Region

-
Weekly operating rate of domestic soda‑ash plants reached 78.31%, rising 2.16% week‑on‑week (76.15% prior week). Output hit 745 800 tons, up 20 500 tons or 2.83% week‑on‑week. Total producer inventory stood at 1.8449 million tons, falling 11 800 tons (‑0.64%) week‑on‑week.
-
Soda‑ash prices saw no major moves. Individual producers adjusted prices flexibly and overall trading was mediocre. Buyers remained prudent and shipments were slow. Without strong fundamental catalysts, soda‑ash market is expected to fluctuate steadily.
Fuel|Petroleum Coke & LNG
National Average Price of Petroleum Coke

-
Domestic petroleum‑coke prices kept rising with fair trading volume.
-
Major refineries saw solid downstream buying and steady shipments; most coke prices held flat while certain grades tightened in supply. Independent refineries showed diverging performance: some faced inventory pressure and offered modest discounts.
-
Operating rates fluctuated narrowly; petroleum‑coke prices are likely to range‑bound in the short run.
National Average Price of LNG

-
Among 133 domestic LNG plants, 68 underwent maintenance / shutdown / suspended reporting / domestic‑only supply. The external operating rate stood at 49%.
-
Rising momentum of domestic LNG prices slowed; overall trading stayed dull. Early‑week higher raw‑gas auction prices plus manageable regional inventories fuelled upward price sentiment. Later, buyers resisted high prices, shipments diverged and some producers faced price pressure. Lacking real demand support, LNG prices are expected to fluctuate within a narrow band.
Aluminum|Aluminum Ingot

-
Domestic spot prices trended down with divergent trading in key regions. In Foshan, trading stayed generally stable; merchants’ processing fees turned down. Downstream restocked on dips and market resilience persisted. Wuxi market remained weak with slow merchant shipments.
Aluminum|Aluminum Profile

-
According to SMM, domestic social inventory of primary aluminium totalled 849 000 tons, down 27 000 tons week‑on‑week.
-
Domestic aluminium futures fluctuated weakly, pulling spot prices along. Downstream entered the traditional hot‑weather off‑season with low operating rates and rigid‑demand‑oriented buying; overall trading was tepid. Macro sentiment keeps swinging. Domestic aluminium market is forecast to stay weak short‑term.